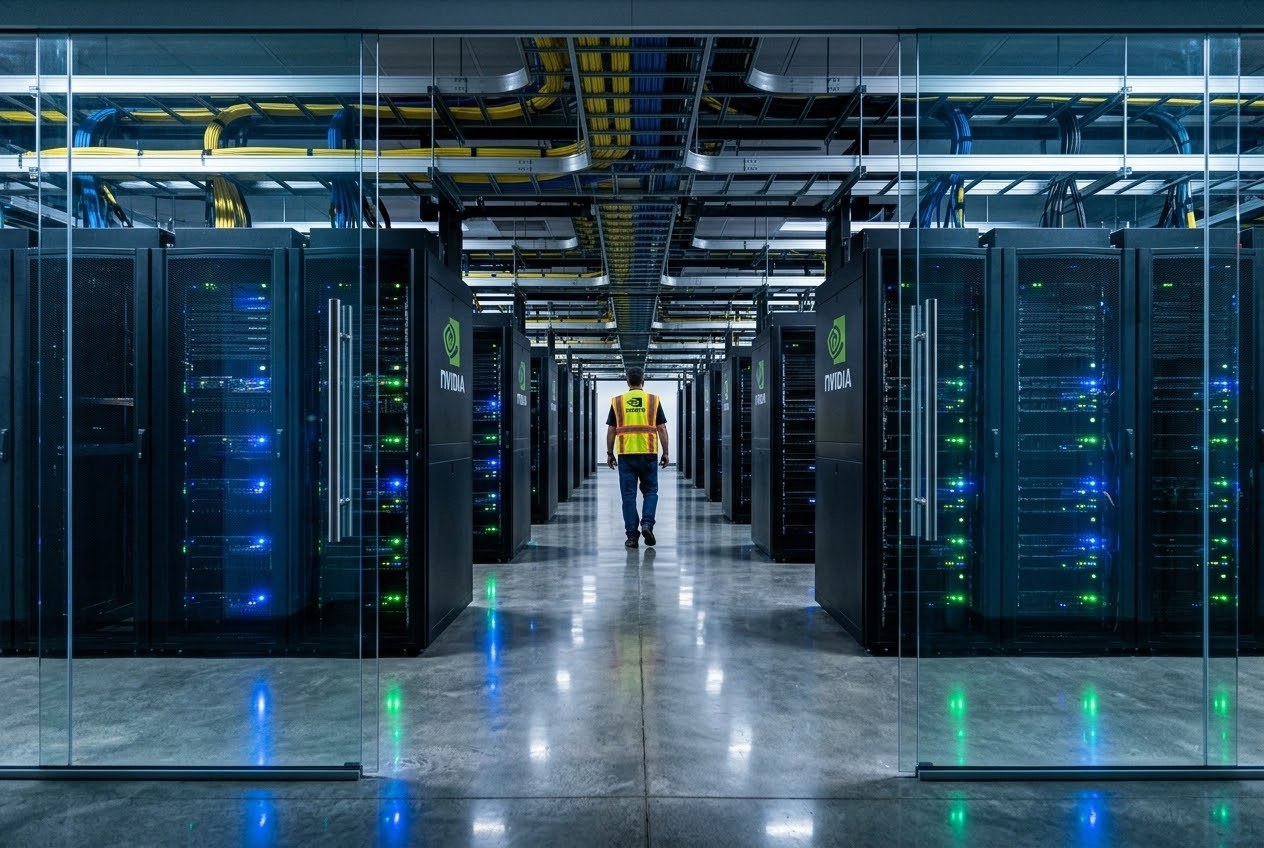
In August, Nvidia announced a plan to line up up to $500 billion in financing for AI infrastructure with six Wall Street firms. It was a big headline, and it is worth a second look now because the structure is unusual. The computing hardware itself is meant to be the collateral. Here is how it works, what is actually committed, and where the risks sit.
What was announced
According to Fortune, Nvidia teamed up with six firms: Apollo Global Management, Blackstone, BlackRock, Brookfield Asset Management, Goldman Sachs, and KKR. CEO Jensen Huang said he approached only those six for the commitment and none turned him down. Deals are expected to start coming to market within months. (Fortune)
How the structure works
The reporting describes special purpose entities that issue debt, both private placements and bonds, and use the money to buy computing capacity that is leased to Nvidia's customers. Individual vehicles could issue tens of billions of dollars in debt at a time, and Nvidia may provide financing support of up to 25 percent of an opportunity, with partners supplying the rest. (Fortune)
In plain terms, a lender is not just lending to a company. It is lending against a pool of chips and the lease payments those chips earn. That is closer to how aircraft or equipment leasing works than to a normal corporate loan. The upside for lenders is predictable lease income. The upside for AI customers is access to capacity without carrying the whole cost on their own balance sheet up front.
The catch
The Motley Fool's take on the deal lays out the weak points clearly. (Motley Fool)
- Short useful life. A power plant lasts decades. A GPU does not. Using chips as collateral is harder when the collateral loses value as newer generations ship.
- Not binding. The agreements are described as memorandums of understanding, which are preliminary handshakes. The $500 billion figure is a target, not money already committed.
- Demand is unproven. It is not yet clear how much appetite AI customers have for this kind of financing.
- Circularity worry. Analyst Felix Wang, quoted by Fortune, said the plan effectively made Nvidia's product cheaper "without really cutting GPU prices." If Nvidia helps finance customers who then buy Nvidia chips, critics see a loop. (Fortune)
The Fool also points out that large cloud companies with huge cash flows, such as Amazon and Alphabet, have been leaning more on bond markets and stock sales to fund AI spending, and argues another funding source can read as a sign of strain more than strength. That is an opinion, but a fair one to weigh. (Motley Fool)
What to watch next
- The first real deals. Reporting says they should reach the market within months. The pricing and terms will show how lenders value the collateral.
- How lenders treat chip age. Watch for shorter loan terms or discounts tied to GPU generations.
- Whether demand follows the headline. The plan only works if customers keep leasing compute at scale.
Bottom line: this is a real structure with real names behind it, but the headline number is a goal. The most useful way to read it is as a test of whether lenders will treat GPUs like durable infrastructure. If you invest, that is a question to watch, not a verdict. Nothing here is financial advice.
Verified October 4, 2026. Figures and quotes come from the cited reporting. The $500 billion figure is a target, not a committed total. The studio's app lineup is at jcmobileappstudio.com/apps.
Sources: Fortune, Motley Fool
Comments
Be kind and stay on topic.
No comments yet. Be the first.