The numbers
- Revenue: $114.5 billion, up 12% from a year ago, the best September quarter Apple has ever had. Earnings per share $2.10, up 14%. Net income $30.7 billion.
- iPhone: $57.58 billion, up 17%. That's the new lineup's launch quarter; the Duo isn't in here at all, because it shipped in October.
- Mac: $10.79 billion, up 24%.
- iPad: $6.23 billion, down 10%, in the quarter right before a new iPad mini, when people wait.
- Wearables, Home and Accessories: $8.30 billion, down 8%. That category keeps shrinking.
- Services: $31.57 billion, up 10%, an all-time high.
- The full fiscal year: about $479 billion, a record. The dividend stays at $0.27 a share, paid November 16 to holders of record on November 12.
Ternus's first call
Ternus took over from Tim Cook on September 1, and this was his first time answering analysts. He didn't change the tone much, which I think was the point. Kevan Parekh, the CFO, did most of the numbers. The only line that sounded new came when an analyst asked about costs, and Ternus said, "What we're seeing with memory pricing right now is unprecedented." Apple doesn't usually use words like that on a call. (Call transcript, Investing.com)
What they said about the iPhone Duo
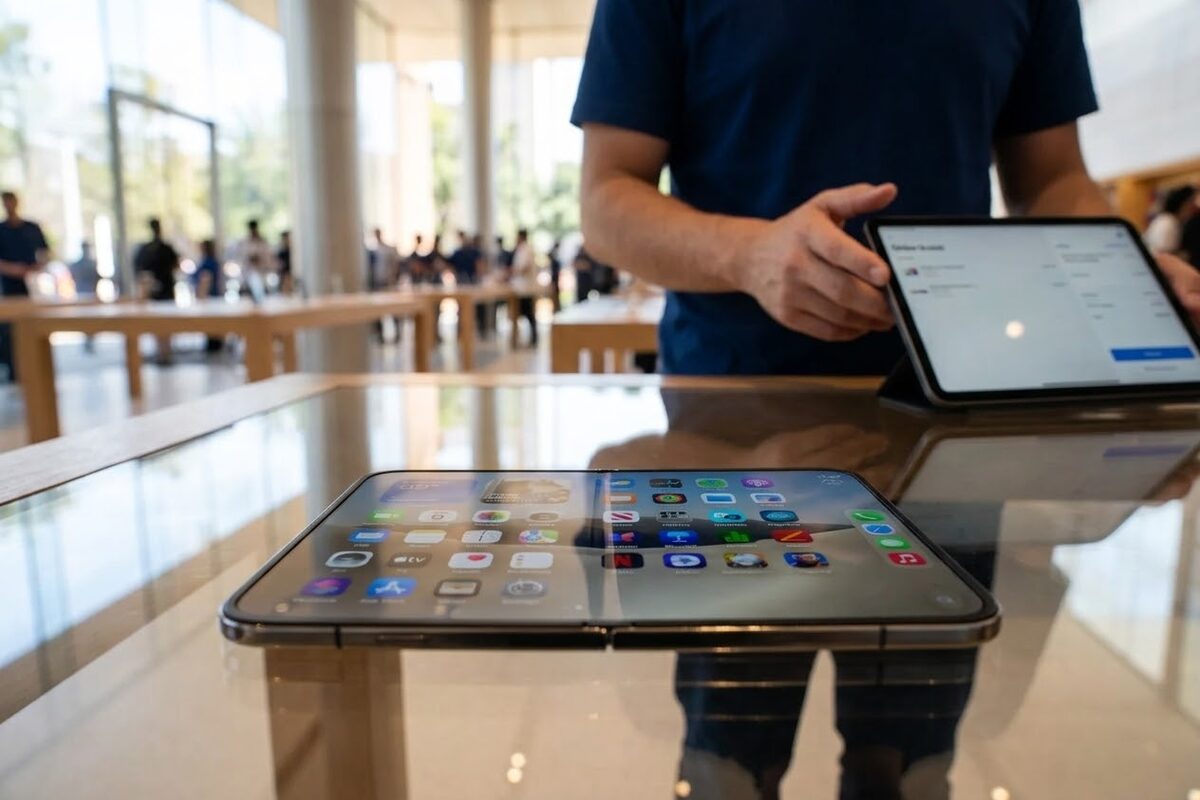
Less than you'd hope. Ternus said Apple has been "thrilled with the early response from reviewers and customers." Sabih Khan, the COO, said the Duo "is constrained as of today" and that "it is really hard to predict when supply and demand will be in balance." That's a polite way of saying no date. If you're trying to buy one, some US configurations were showing delivery in late January 2027 last week, and UBS put average lead times around 89 days. (Techloy, UBS via MacDailyNews)
On the display and hinge complaints I covered on Monday, Apple said a very small share of units have come back for display issues and that it is replacing them. Apple didn't give a number and nobody outside Apple has one either, so treat "very small" as Apple's word, not a measured failure rate. Some of the coverage I read said Ternus promised to ramp hinge production and extend warranty support. I couldn't find either in the transcript.
The number that moved the stock
For the December quarter, Apple guided revenue up 7% to 10%, which would be another record, and Services up 8% to 9%. Then it guided gross margin to 45% to 46%. The quarter that just ended was 47.9%, and about a point of that came from tariff refunds that won't repeat. Parekh said memory is most of the rest of the drop, and that "we expect the memory costs to continue to be a challenge for us" through the holidays.
Two points of margin on a quarter that big is a couple of billion dollars of profit. That's why a company that just beat on almost every line closed down 1.8% at $338.32 on Monday, slid about another 2.8% after hours, and closed Tuesday at $331.90. (INDmoney, StockAnalysis)
What I take from it
- If you own the stock: nothing here says Apple is in trouble. It says Apple is choosing to eat higher memory costs this holiday instead of raising prices on you right before Christmas. That protects the customer and costs the shareholder a little, for now. The thing to watch in January is whether memory costs keep climbing into 2027, because Apple hinted they will.
- If you want a Duo: order the configuration you want now and accept the wait, or wait for the reports on how the first units hold up. Don't pay a reseller markup for a first-generation hinge.
- If you're buying a Mac or iPhone this month: prices didn't move on this call. Apple absorbing costs is the reason they didn't.
None of this is investment advice. It's how I read the report, nothing more.
Verified November 4, 2026, from Apple's press release, 9to5Mac, the call transcript, INDmoney, Hypebeast, Techloy and StockAnalysis. Some early write-ups put Mac revenue at $9.6 billion and called Parekh the incoming CFO; Apple's release says $10.79 billion and he is the CFO. Quotes are from the published transcript. Written Wednesday for Thursday morning.
Comments
Be kind and stay on topic.
No comments yet. Be the first.